Strong occupational demand despite an increasingly constrained supply picture leads to selective rental growth.
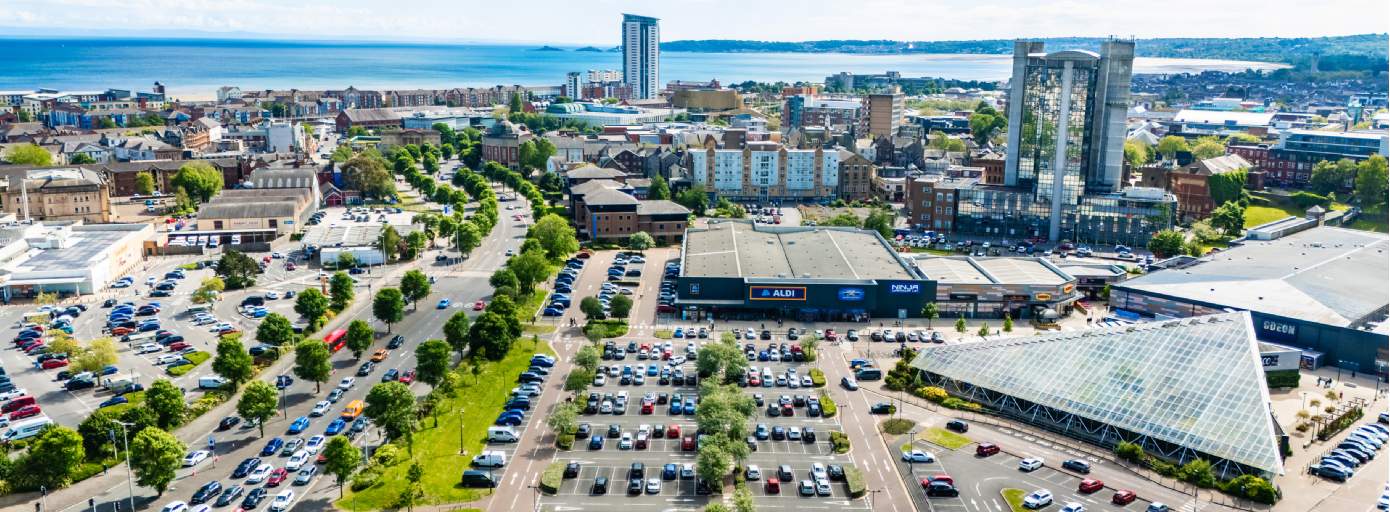
The UK retail warehouse market continues to be defined by a structural shortage of available space. Outside selected roadside food and beverage schemes, drive-thru formats and bespoke discount grocery development, very little new retail stock is being delivered. Occupiers are therefore increasingly reliant on space becoming available through normal occupational churn.
That churn has reduced materially. Across the Savills dealbook of new lettings, regears and renewals, only 8% of occupiers vacated between 2023 and 2026, with 92% renewing their lease commitments. Retailers are increasingly reluctant to relinquish successful stores, recognising that securing representation on a strong retail park has become significantly more difficult. When they do move, it is typically to right-size, improve configuration or upgrade their position within a scheme, rather than exit the market altogether.
Weaker letting volumes should be viewed in this context. New lettings totalled 721 in 2025, below the long-run average of 847, while activity has remained subdued in 2026. With little additional supply and limited churn, it is important to stress the market is constrained by a lack of available space rather than any shortage of occupier appetite.
Even the headline vacancy rate overstates availability. Vacancy has fallen from 4.3% at the end of 2025 to 3.9% today, but 47.1% of vacant floorspace has been empty for at least three years, constrained by planning restrictions or no longer suited to modern occupational requirements. Excluding this stock reduces effective vacancy to 2.1%, equivalent to around 706,000 sq m of genuinely available accommodation. Against average annual net take-up of 743,000 sq m over the past three years, the market holds less than one year’s effective supply.
The administrations of Homebase and Carpetright in 2024 provided a temporary test of the depth of occupier demand. While a tranche of larger units returned to the market and briefly lifted vacancy, strong pent-up demand from occupiers seeking expansion opportunities meant much of the space was absorbed rapidly. The speed at which these units were re-let underlined the shortage of suitable space available across the market. In the absence of meaningful development, the sector has become increasingly reliant on isolated restructuring and insolvency events to create the leasing opportunities that occupiers are actively seeking.
Rental performance is more nuanced at the larger-format end of the market. Units exceeding approximately 1,850 sq m recorded rental growth of 17.8% in 2024 and a further 8.2% in 2025, supported by the competition for former Homebase and Carpetright stores. In 2026, however, average rents in this size bracket have fallen by 10.3% as many of the stronger units have already been absorbed, leaving a greater proportion of secondary space to transact. Even after that adjustment, rents remain 14.3% above pre-administration levels.
Wider rental growth has been more restrained. Net effective retail warehouse rents increased by 1.7% year to date, following growth of just 0.1% in 2025, as macroeconomic uncertainty, rising occupational costs and pressure on household spending limited occupiers’ ability to absorb substantial increases. Geography and asset quality remain important. Structurally under-supplied locations achieved average rents of €270 per sq m in 2025, compared with €254 per sq m in markets with above-average provision.
The UK demonstrates how constrained supply can sharpen the value of well-located, adaptable stock without producing uniform rental growth. Retailer retention remains high, effective vacancy is exceptionally low and securing vacant possession can prove harder than generating demand. For investors, the opportunity increasingly lies where genuine scarcity, occupier depth and asset quality coincide.
In many respects, this reflects a later stage of the same evolution occurring elsewhere in Europe. While development continues to support occupier growth across Central and Eastern Europe and parts of Southern Europe, existing assets are increasingly required to absorb demand. Similar occupational momentum can therefore translate into different investment themes: expansion in less mature markets, and the growing value of scarce, adaptable stock where supply is harder to expand.
Minimal development, exceptionally low effective vacancy, limited occupier churn and strong, broadbased occupier appetite mean softer trading is more likely to moderate the pace of rental growth than alter its direction.
Sam Arrowsmith, Director, UK Retail Research
Read the other articles within European Retail Warehousing below